BB
BB unveils first quarterly monetary policy, keeps policy rate unchanged at 9.5%
Bangladesh Bank (BB) on Wednesday unveiled its first-ever quarterly Monetary Policy Statement (MPS) for October–December quarter of FY 2026–27, keeping the benchmark policy interest rate unchanged at 9.50 % to curb inflation, while acknowledging that elevated borrowing costs continue to suppress private sector credit growth.
The central bank transitioned to a quarterly monetary policy framework from the previous half-yearly cycle in line with condition set by the International Monetary Fund (IMF).
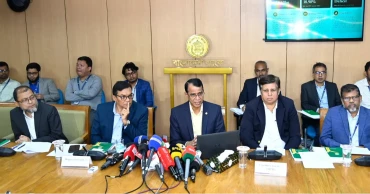
Deputy Governor Dr. Md. Habibur Rahman formally announced the monetary policy at a press briefing held at the Jahangir Alam Conference Hall of the central bank's headquarters in Motijheel.
Under the policy decision, the Standing Lending Facility (SLF) rate remains unchanged at 11%, while the Standing Deposit Facility (SDF) rate stands at 7.50 %.
Highlighting the state of credit flow, the central bank noted that higher financing costs resulting from the tight monetary stance, alongside energy shortages, infrastructure bottlenecks, and investment uncertainty, have severely constrained credit expansion.
Private sector credit growth slowed to a sluggish 4.75 percent in August 2026, reflecting weak investment demand, elevated borrower risks, and structural vulnerabilities in the banking sector, where the non-performing loan (NPL) ratio reached 32.78 percent in June 2026.
The Deputy Governor expressed optimism that private sector credit growth would pick up during the October–December quarter as liquidity conditions adjust.
Explaining the rationale behind keeping the rate unchanged, the central bank stated that premature monetary easing could reignite inflation expectations.
Although headline inflation eased to a 10-month low of 8.26 percent in August 2026—driven by food inflation slowing to 7.02 percent—non-food inflation remained elevated at 9.32 percent.
Underlying price risks linger due to global energy price volatility, potential supply disruptions in the Strait of Hormuz, recent domestic fuel price hikes, and fiscal pressures from the national pay scale implementation.
On overall economic performance, BB cited that real GDP growth for FY26 stood at an estimated 4.14 percent, though Q3 FY26 growth fell to 2.2 percent alongside a 0.28 percent contraction in industrial output.
For FY27, the World Bank projects GDP growth at 4.6 percent, while the IMF has revised its projection down to 3.5 percent from 4.3 percent.
To support growth without undermining price stability, the central bank highlighted a Tk 60,000 crore stimulus package, which includes Tk 20,000 crore for reopening closed factories, alongside active refinance schemes for CMSMEs, agriculture, and export diversification.
Regarding the external sector, BB reported that robust remittance inflows—growing by 18.90 percent in early FY27—and a broadly stable exchange rate continue to bolster foreign exchange reserves and help buffer against imported inflation.
1 hour ago

BB eases external borrowing rules for foreign-owned industries
Bangladesh Bank has granted general permission for fully foreign-owned industrial enterprises, operating both within and outside specialised economic zones, to borrow directly from their parent companies, associates, or shareholders abroad, in a move aimed at easing access to finance for foreign investors.
The central bank's Foreign Exchange Investment Department (FEID) issued the directive through FEID Circular on Wednesday revising earlier provisions under FE Circular No. 34 of September 2, 2025, which governed external borrowing by such enterprises.
Under the new provisions, foreign-owned manufacturing and service enterprises outside specialised zones such as EPZs, PEPZs, EZs and HTPs can now avail short-term borrowing of less than one year without prior Bangladesh Bank approval, provided the funds are used for genuine business purposes.
The circular allows two options for such borrowing-enterprises may take interest-free loans for general working capital needs, excluding input procurement, with no central bank clearance required even for principal repayment.
Alternatively, they may opt for cost-bearing loans in convertible foreign currencies, including for input procurement, but the all-in cost of such borrowing must not exceed 3 percent per annum.
These loans must be repaid in a single bullet payment at maturity and may be rolled over, provided the total tenor, including rollovers, does not exceed three years from the date of initial drawdown. Such short-term facilities cannot be converted into medium or long-term loans.
Authorized Dealers (ADs) have been directed to report all such transactions to the FEID within one week of execution, in addition to routine reporting requirements.
2 months ago

BB grants exemption to Shinepukur Ceramics to open LCs with 100% margin until Dec 2027
Bangladesh Bank (BB) has exempted Shinepukur Ceramics Limited from a specific restrictive provision allowing the company to open Letters of Credit (LC) with a 100 percent margin through Sonali Bank PLC to import essential raw materials.
The central bank issued an official directive on Tuesday (July 14), signed by Deputy Governor Dr. Md. Kabir Ahmed and circulated by Director Md. Bayazid Sarker of the Banking Regulation and Policy Department-2, notifying the top executives of all scheduled banks across the country.
Bangladesh Bank declared that the restrictions under Section 27 Ka(3) of the same act will remain suspended for Shinepukur Ceramics Limited until December 31, 2027.
The central bank noted that the special regulatory waiver has been granted strictly on humanitarian and economic grounds to ensure the continuity of the factory’s industrial production and to protect the employment of its massive workforce.
However, the apex bank attached strict conditions to safeguard the state-owned lender's funds:
Designated Account Tracking: Shinepukur Ceramics Limited must deposit all its operational and business income into a single, specific designated bank account.
Proportionate Debt Clearance: Sonali Bank PLC must regularly recover its outstanding dues from that specific account on a proportionate basis.
Zero State Liability: The central bank explicitly clarified that no financial liability or obligation will be passed on to the Finance Division or Bangladesh Bank against this special credit facility.
No Future Bailouts: The directive strongly stated that Sonali Bank PLC, the Government, or any involved entity cannot claim any financial assistance or bailouts from Bangladesh Bank regarding this arrangement in the future.
2 months ago

BB directs banks to prioritize smart card holders, rain-hit farmers for agro-loans
In a major boost to financial inclusion and disaster recovery, Bangladesh Bank (BB) on Tuesday directed all scheduled banks to prioritize marginal and landless farmers holding
"Farmer Smart Cards" and those recently hit by pouring summer rains for low-interest loans.
The central bank issued a comprehensive circular on the matter to the managing directors and chief executive officers of all commercial banks. The directive, signed by Md. Iqbal Mohsin, Director of the Financial Inclusion Department (FID) of BB, aims to streamline the disbursement of credit under the central bank's ongoing refinancing scheme tailored for low-income professionals, marginal farmers, and small businesses holding Tk 10, Tk 50, or Tk 100 bank accounts.
The central bank's move aligns with the government’s recent "Farmer Smart Card Policy-2025," an initiative spearheaded by the Department of Agricultural Extension (DAE) to bring the nation's farmers under an integrated digital database.
According to the new circular, banks must offer preferential treatment to card-holding marginal and landless farmers when opening Tk 10 bank accounts and processing loans under the refinancing framework. Financial analysts note that blending this digital database with the formal banking system will significantly enhance transparency in targeted agricultural subsidies, incentives, and government aid, making it easier to weed out middlemen and identify genuine smallholders.
However, the regulator cautioned banks against creating an artificial barrier, explicitly stating that eligible, impoverished farmers who are yet to receive their smart cards must not be excluded from the credit facility.
The central bank’s directive also addresses immediate climate vulnerabilities following abnormal summer downpours that decimated standing crops across the country, particularly the ripe Boro paddy in wetland ecosystems.
Recognizing the severe financial shock to rural households, the central bank ordered immediate, hassle-free credit flows to help affected farmers recover and prepare for the upcoming cropping cycle.
The circular placed a special emphasis on the hard-hit ‘haor’ (wetland) districts, explicitly naming Sylhet, Sunamganj, Habiganj, Kishoreganj, Netrokona, and Mymensingh for immediate rehabilitation assistance, while keeping the window open for affected smallholders in other districts. Central bank officials warned that any delay in credit deployment could jeopardize national agricultural productivity, trigger rural distress, and impact food security.
The specialized refinancing scheme serves as a crucial regulatory bridge for populations traditionally locked out of commercial banking due to a lack of collateral. By offering low-interest funds to banks, the central bank effectively absorbs sectoral risks, incentivizing financial institutions to cater to small-ticket borrowers.
Policy experts view this latest double-barreled policy modification—linking digital identity cards to agro-credit and mandate-driven climate resilience funding—as a mature milestone in Bangladesh's financial inclusion journey, vital for maintaining macroeconomic stability amid growing environmental challenges.
3 months ago

BB directs banks, MFS to ensure uninterrupted digital transactions during Eid
Bangladesh Bank (BB) has directed all scheduled banks, Mobile Financial Services (MFS) providers and payment system operators to ensure uninterrupted and secure digital transactions during the Eid-ul-Fitr holidays.
In a circular issued on Monday, the central bank instructed financial institutions to maintain round-the-clock operations across electronic payment platforms to facilitate the public during the festive period.
Banks have been asked to keep Automated Teller Machines (ATM) fully functional, with sufficient cash supply, prompt resolution of technical issues, 24/7 security, and regular monitoring by officials. Point of Sale (POS) and QR code-based payment services must also remain operational, alongside increased awareness among merchants and customers to prevent fraud.
The central bank emphasised secure Internet banking and online e-payment gateways including mandatory Two-Factor Authentication (2FA) for “Card not Present” transactions.
Banks were also instructed to immediately credit beneficiary accounts upon receiving settlement reports with '85' response codes.
For MFS providers such as bKash, Nagad, and Rocket, the BB directed uninterrupted service across all platforms and adequate cash availability at agent points for withdrawals.
To protect consumers, the central bank mandated immediate SMS alerts for transactions of any amount, strengthened technical safeguards against cyber threats, and functional help lines to assist customers. Institutions were also urged to run public awareness campaigns through mass media to encourage safe electronic payments.
6 months ago
Card transactions in Bangladesh jump 143% in five years: BB
Card-based transactions in Bangladesh have surged by about 143 % over the past five years, according to the latest report of Bangladesh Bank.
Data from the central bank shows that total card transactions stood at Tk 20,625 crore in January 2021.
The figure rose sharply to Tk 50,044 crore by December 2025, highlighting the rapid expansion of cashless transactions across the country.
The report also shows a significant rise in the number of cards in circulation.
In January 2021, the total number of cards was 2.40 crore which increased to more than 5.18 crore by December 2025, marking a 115 percent growth during the period.
At present, 61 banks and one non-bank financial institution (NBFI) are providing card services in Bangladesh.
Among them, 55 banks offer debit card facilities to their customers.
An analysis of consumer spending patterns indicates that credit card holders spent Tk 3,930 crore within the country in December alone last year.
Of this amount, the largest share Tk 1,740 crore was spent at departmental stores.
The report also analysed spending by foreign cardholders in Bangladesh, showing that citizens of the United States accounted for the highest expenditure in the country.
Nationals from the United Kingdom, India, Mozambique, Australia, Canada and Saudi Arabia also made notable contributions to foreign card spending.
6 months ago

BB orders strict loan data updates to bar defaulters from election race
Bangladesh Bank has ordered all scheduled banks to promptly update loan repayment data as prospective MP candidates, many of them business and political figures, scramble to clear defaults and overdue installments to remain eligible for the national polls.
Managing directors of various banks, non-bank financial institutions (NBFIs), and Bangladesh Bank officials said they are receiving a surge in applications for loan regularisation.
In response, the Credit Information Bureau (CIB) of Bangladesh Bank (BB) has issued a strict directive to all banks and financial institutions nationwide, ordering rapid updates of loan-related data to confirm the financial eligibility of potential candidates.
Bangladesh Bank eases SME loan rules for refinance fund amid rising defaults
Bangladesh Bank officials said on Saturday that even if a borrower secures a stay order from a court, financial institutions must report the accurate status of the loan to the CIB without any alteration.
The central bank emphasised that there will be no scope to conceal information or offer ‘arbitrary’ concessions.
A special meeting was held on October 29 with CIB representatives from all banks and NBFIs, where institutions were informed of the government’s firm instruction to complete loan data updates before the election to ensure no loan defaulter can contest.
“The Bangladesh Bank has made it clear that the government will not allow any loan defaulter to become a candidate in the upcoming election,” said a CIB official.
Arif Hossain Khan, Executive Director and spokesperson of Bangladesh Bank, said the central bank is updating customers’ loan statuses as per government instructions.
He added that providing updated credit information to Bangladesh Bank is a routine responsibility of banks.
Govt may compensate investors in 5-bank merger: Bangladesh Bank
The central bank has also directed all institutions to strictly follow existing rules concerning borrowers attempting to reschedule long-overdue defaulted loans ahead of the election. No exceptions, special privileges, or rule violations will be permitted for rescheduling.
All financial institutions, particularly those yet to submit their default data to the CIB, have been ordered to do so immediately. Updated reports detailing the full status of all new and ongoing loans, based on month-end outstanding balances, are mandatory.
Banks have been specifically instructed to update the following information:
Accounts of ongoing and settled loans, along with accurate balances and classification status,
Maturity dates and overdue balances, Number and value of defaulted instalments, and details of installment payments or recoveries.
To ensure round-the-clock verification of loan information for potential candidates, Bangladesh Bank has directed every bank branch to appoint a dedicated officer. Their names and mobile numbers must be submitted to the central bank.
Bangladesh Bank directs MFS providers to halt online gambling transactions
Electoral law clearly states that a candidate will be disqualified if their bank loan status is not classified as ‘regular’ up to seven days before the submission of nomination papers.
Officials concerned believe this rigorous initiative by Bangladesh Bank will play a decisive role in preventing loan defaulters from securing nominations ahead of the election.
10 months ago

BB-Dollar: Taka loses 12.72% value in 2024 as dollar strengthens
The Bangladesh Bank (BB) increased the US dollar exchange rate by Tk12 in 2024, resulting in a 12.72% depreciation of the local currency, the taka, over the year.
A central bank data analysis shows that the central bank fixed the dollar exchange rate at Tk122 on December 31, compared to Tk110 in January 2024. This indicates a Tk12 increase in the dollar's price and a corresponding 12.72% loss in the taka's value.
Bangladesh has been struggling with a dollar crisis for three consecutive years, driving up the dollar's price and weakened the taka further.
Meanwhile, banks have also increased the dollar price by Tk2 for both buying and selling. Later, the taka's value dropped by another Tk2. Banks will now sell the dollar to customers for sectors such as imports, loan repayments, and others at a maximum rate of Tk122.
Bangladesh Bank increases crawling peg rate by Tk 2
Ashraf Ahmed, former president of the Dhaka Chamber of Commerce and Industry (DCCI), noted that the banks' move to raise the dollar price will escalate import costs. As a result, the price of imported goods will rise since more money is needed to pay for them, he said.
Talking to UNB, Dr Tawfiqul Islam Khan, Senior Research Fellow at the Centre for Policy Dialogue (CPD), highlighted the inflationary impact of the taka's depreciation. The devaluation by Tk2 means that the prices of goods will inevitably increase. This, coupled with the rising cost of imported goods, will add further pressure on inflation, he pointed out.
1 year ago

BB drafting separate rules for Islamic banking; ‘bankers divided’
Bangladesh Bank (BB) is drafting separate rules to regulate the Islamic banking system in the country, a move that has stirred mixed reactions among bankers and analysts.
An Executive Director of the central bank, who is involved in drafting the rules, said that under the proposed regulations, conventional banks would no longer be permitted to offer Sharia-based banking services directly. Instead, banks would need to establish subsidiary institutions to operate Islamic banking.
“If this law comes into effect, conventional banks will not be able to provide Sharia-based banking services,” the official added.
DSE trading ends with upward trend on Sunday
Some bankers, however, argue that this move could contradict Bangladesh’s long-standing commitments under the Islamic Development Bank (IDB).
The country became a signatory to the IDB in the 1980s, which facilitated the introduction of Sharia-based banking within conventional banks.
Mohammad Abdul Mannan, former Managing Director of Islami Bank Bangladesh, expressed concerns about the implications of the proposed regulations. “New law (regulations) regarding establishment of subsidiaries instead of Islamic banking windows for conventional banking will be contradictory with the declaration of IDB,” he told UNB.
Instead of conflicting with the IDB’s declaration, he said, the central bank could set up a dedicated department to monitor Sharia compliance and fund management in Islamic banks.
Syed Mahbubur Rahman, Managing Director of Mutual Trust Bank, highlighted the current success of Islamic banking windows and branches operated by conventional banks.
DSE index gains 30.88 points as 211 stocks rise in early trading
“All the banks that are doing Islamic banking through windows or branches are in good condition. I don't think that making one Islamic and the other traditional will yield good results. If we prepare separate balance sheets and income statements and follow the instructions of the central bank properly, [it] would be more effective and time-befitting,” he said.
Mahbubur Rahman went on to say, “If they monitor properly, and if the Sharia board is in place properly, then I think there should be no problem here.”
But some analysts view the situation differently.
While acknowledging the financial viability of Islamic banking under conventional banks, they pointed out challenges related to Sharia compliance.
Former Chairman of the Association of Bankers Bangladesh (ABB) Mohammad Nurul Amin questioned the integrity of current practices. “The balance sheet of the conventional bank is also the same as that of the Islamic branch. How much is Sharia-based and correct?” he asked.
Dr Toufiq Ahmed Chowdhury, former Director General of the Bangladesh Institute of Bank Management, supported the idea of separate rules, questioning the authenticity of Islamic banking in its current form.
He said, “I personally support a separate law. Here, we are not actually doing Sharia-based banking to conduct business; we are doing it to make money, taking some money from people in the name of Islam. When it is launched, is it truly Islamic banking? Not even 1.0 percent of the total portfolio is PLS. So, why is it being called Islamic banking?”
18 banks at risk due to potential loan defaults by top 3 borrowers: Bangladesh Bank
According to central bank officials, the draft law is still under review, and no final decision has been made.
Husneara Shikha, Executive Director and spokesperson for BB, stated that stakeholder consultations are essential before finalising the law.
“When making a law, various types of stakeholder consultation and analysis [have] to be done. What are the international policies? At the international level, conventional banks never open Islamic windows,” she explained.
The Islamic Bank Company Act will be finalised after incorporating opinions from all stakeholders.
Islamic banking is a banking system aligned with the spirit, ethos and values of Islam, operating in accordance with the principles outlined by Islamic Shariah.
Currently, Bangladesh has 10 fully-fledged Sharia-based banks, in addition to 30 conventional banks offering Islamic banking services. These conventional banks operate 33 Islamic banking branches and around 700 windows for Sharia-based services.
1 year ago

BB announces 10% incentive for exporting agro-processed products
Bangladesh Bank has introduced a 10 percent cash incentive for the export of agricultural and agro-processed products.
This incentive will apply specifically to juices and drinks made from locally produced fruit pulp, allowing exporters in this sector to benefit from the support.
The Foreign Exchange and Policy Department of BB issued a notification on Thursday, outlining new guidelines for cash assistance in the export of agricultural (vegetables/fruits) and processed (agro-processing) agricultural products.
According to the notification, exporters will now receive cash assistance for exporting juices and drinks made using locally sourced fruit pulp.
1 year ago